LPPSA financing calculator for civil servants
Are you a government servant in Johor? Estimate how much LPPSA may finance, your monthly instalment at 4%, and whether your total salary deductions stay within the 60% limit.
Quick answer
How much can LPPSA finance in 2026?
Since 4 Oct 2026 LPPSA can finance up to RM1 million (previously RM750,000), up to 100% of the price or valuation, whichever is lower, at a 4% profit rate (4.5% on the part above RM750,000). A first financing can run up to 35 years and must end by age 90, and the instalment can be up to 60% of net income. For example, a net income of RM3,800 allows about RM2,280 a month, which over 35 years at 4% repays roughly RM515,000.
Key facts (5)
- SPPSAi (Islamic): 7% ceiling rate with a rebate to an effective 4%.
- Second financing: up to 30 years and 50% of net income. Skim Muda: up to 40 years.
- Total debt can be up to 80% of basic salary plus fixed allowances.
- Payroll rule: total salary deductions must stay below 60% of basic salary plus fixed allowances.
- For confirmed permanent civil servants only; contract staff and pensioners are not eligible.
Updated: · Reviewed by Rumah Bumi Johor
Calculator
Estimated maximum LPPSA financing
RM 0
- Financing for this house
- -
- Monthly instalment
- -
- Tenure used
- -
- Shortfall you pay yourself
- -
- Highest instalment allowed
- -
- Net income used
- -
- Total deductions after LPPSA
- -
Estimate only. LPPSA decides the approved amount based on your full payslip, the property valuation and its own rules. Updated: Nov 2026
Assumptions and rules used
- Profit rate 4% a year on the first RM750,000 and 4.5% on the part above (blended rate, from 4 Oct 2026), monthly reducing balance (SPPSA). SPPSAi: 7% ceiling rate with rebate to an effective 4%.
- Maximum financing RM1,000,000 from 4 Oct 2026 (previously RM750,000). Up to 100% margin. Skim Muda: we use RM750,000 as stated in 2026 guides; confirm with LPPSA.
- Tenure: first financing up to 35 years, second up to 30 years, Skim Muda up to 40 years, and financing must end by age 90.
- Repayment capacity: instalment up to 60% of net income for first financing (50% for second), and total debt up to 80%. Here net income = basic salary + fixed allowances − existing deductions, and the 80% test uses basic salary + fixed allowances. LPPSA also deducts statutory items (for example income tax), so the real figure can be lower.
- Salary deduction limit: total deductions below 60% of basic salary + fixed allowances (Accountant General payroll rule, 1PP WP9).
- Not included: MRTT/MLTT takaful, legal fees, stamp duty and valuation fees. The house must be valued by LPPSA; financing is based on the lower of price and valuation.
Homes in your budget
New projects in Johor in this price range. WhatsApp us for the latest prices and units.
 KSL Ceros Residences @ Nusa IdamanIskandar Puteri, Bukit Indah & Second LinkBumi: SPA price 15% lower
 KSL Austin Legacy @ Seri AustinMount Austin, Tebrau & PonderosaBumi: SPA price 15% lower
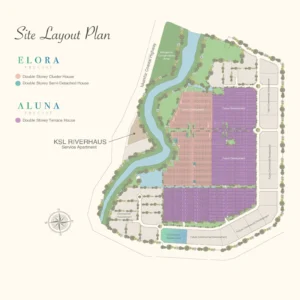 KSL RiverhausIskandar Puteri, Bukit Indah & Second LinkBumi: SPA price 15% lower
 KSL D’Secret Garden 2 @ KempasTampoi & KempasBumi: SPA price 15% lower
 Meadow Heights @ Bandar TiramMount Austin, Tebrau & PonderosaBumi: SPA price 15% lower
 Aethera ResidencesJB City Centre & RTSBumi: SPA price 15% lower
 Bandar Tiram 3 Landed HomesMount Austin, Tebrau & PonderosaBumi: SPA price 15% lower
 The Eclipse Johor BahruJB City Centre & RTSBumi: SPA price 15% lower
Full guide
Read the full guide
How does LPPSA work out how much you get?
LPPSA looks at how much you can repay each month, not only at your grade. It takes your basic salary and fixed allowances, removes the deductions you already have, and then allows an instalment of up to 60% of what is left for a first financing. The amount it will finance is the sum that this instalment can repay at 4% over your tenure, up to the ceiling of RM1 million. If your house costs less than that, LPPSA can finance up to 100% of the price or the valuation, whichever is lower, so many civil servants do not need a 10% down payment.
For example, a teacher with a basic salary of RM3,500, fixed allowances of RM900 and RM600 of other deductions has a net income of RM3,800 in this calculator. Sixty percent of that is RM2,280 a month, which over 35 years at 4% repays roughly RM515,000. If the house costs RM350,000, the instalment is only about RM1,550.
Why does the 60% salary deduction limit matter?
Even if LPPSA approves you, your payslip has its own limit. The Accountant General processes deductions only while the total stays below 60% of basic salary plus fixed allowances. A new LPPSA instalment on top of a car loan and a cooperative loan can push you over that line. When that happens, the lower-priority deductions are not processed through your salary and you must pay them yourself. The result box tells you where you stand, so you can settle a small loan first or choose a cheaper house.
LPPSA or a bank loan?
The 4% fixed rate, 100% margin and salary deduction make LPPSA attractive, but processing can take longer and some developers prefer bank loans for fast bookings. Ask the developer early whether the project accepts LPPSA. You can get LPPSA financing twice in your career; check the current second-financing rules with LPPSA.
Read more: how to apply for LPPSA, the RM1 million ceiling, LPPSA vs a bank loan and Skim Muda and second financing.
Related reading: new homes in Johor RM300k–RM500k, all projects.
Frequently asked questions
What is the LPPSA profit rate?
LPPSA charges 4% a year on a monthly reducing balance for financing up to RM750,000. Since 4 Oct 2026, the part above RM750,000 (up to RM1 million) is charged 4.5%, so the overall rate is a blend, for example about 4.03% for RM800,000. For the Islamic option (SPPSAi) the ceiling profit rate is 7%, but LPPSA gives a rebate (ibra) so the effective rate is 4%, as long as you do not fall into arrears.
Is the RM1 million ceiling already in force?
Yes. The higher ceiling from Budget 2026 took effect on 4 Oct 2026, based on the LPPSA notice reported by EdgeProp. Before that the maximum was RM750,000. The ceiling is a maximum, not an automatic amount: your approved figure still depends on your income, commitments and the property valuation.
How long can the financing period be?
First financing can run up to 35 years (420 months) and must end by age 90, whichever comes first. Second financing is up to 30 years. Skim Pembiayaan Perumahan Muda for applicants aged 30 and below allows up to 40 years.
What is the 60% salary deduction limit?
For civil servants, the Accountant General processes payroll deductions only while your total deductions stay below 60% of basic salary plus fixed allowances. LPPSA instalments have high priority, but if your total goes above 60%, some other deductions may have to be paid directly instead of through your payslip.
Can contract staff or pensioners apply?
No. LPPSA is for confirmed permanent public servants, including the police and armed forces, usually with at least one year of service. Contract staff, part-time staff and pensioners are not eligible for new financing.
Sources: MyGOV: public sector housing financing (4%, 35 years or age 90) (seen 17 Nov 2026); EdgeProp: RM1 million LPPSA ceiling from 4 Oct 2026 (2 Oct 2026); PropCashflow: LPPSA rules (60%/50% and 80% tests, tenure) (Jul 2026); Accountant General (JANM): 60% salary deduction FAQ (seen 17 Nov 2026)
Civil servant posted to Johor? Tell us your grade, area and budget. We list projects that accept LPPSA.
WhatsApp 018-989 6881