Home loan and DSR calculator
Work out the monthly instalment for a home in Johor, or how much a bank may lend you based on your salary and commitments (DSR). Works for conventional loans and Islamic home financing.
Quick answer
How much is the monthly instalment for a RM450,000 home?
For a RM450,000 home with a 90% loan (RM405,000) at 4% a year over 35 years, the monthly instalment is about RM1,793. Over the full tenure you pay about RM753,000, of which roughly RM348,000 is interest or profit. Banks usually approve the loan if your total commitments stay within a DSR of 60% to 70% of net income.
Key facts (5)
- Margin of financing: up to 90% for the 1st and 2nd home, 70% from the 3rd housing loan (Bank Negara Malaysia, Nov 2010).
- Maximum tenure 35 years (Bank Negara Malaysia, Jul 2013); most banks want the loan to end by about age 70.
- Credit cards count as 5% of the total limit per month, even with no balance.
- Every RM100 of monthly commitment you clear adds roughly RM22,500 to the loan you can get at 4% over 35 years.
- Conventional loans and Islamic financing with a variable rate use the same reducing balance formula.
Updated: · Reviewed by Rumah Bumi Johor
- Loan / financing amount
- RM 0
- Down payment
- RM 0
- Total paid over the tenure
- RM 0
- Total interest / profit
- RM 0
- Interest / profit in year 1
- RM 0
Estimate only. Actual rates depend on the bank and your profile. Updated: Nov 2026
Loan balance by year
First 12 months: where each payment goes
| Month | Payment | Interest / profit | Principal | Balance |
|---|
- Net income used
- RM 0
- Current commitments
- RM 0
- of which credit card (5% of limit)
- RM 0
- Current DSR
- 0%
- Maximum new monthly instalment
- RM 0
- Maximum loan / financing
- RM 0
Estimate only. Actual rates depend on the bank and your profile. Updated: Nov 2026
Assumptions and rules used
- Reducing balance formula, the same for conventional loans and Islamic financing with a variable rate. Default rate 4.00% a year, which you can change (0% to 15%).
- Margin of financing: up to 90% for the first and second residential property, 70% from the third outstanding housing loan (Bank Negara Malaysia, Nov 2010).
- Tenure up to 35 years (Bank Negara Malaysia, Jul 2013), and most banks want the loan to end by about age 70.
- DSR = monthly commitments divided by net monthly income. Credit cards are counted as 5% of the total limit. Banks set their own DSR limit, commonly 60% to 70% depending on income.
- Not included: MRTA / MRTT, legal fees and stamp duty financed into the loan, and any lock-in or early settlement fee.
Homes in your budget
New projects in Johor in this price range. WhatsApp us for the latest prices and units.
 KSL Ceros Residences @ Nusa IdamanIskandar Puteri, Bukit Indah & Second LinkBumi: SPA price 15% lower
 KSL Austin Legacy @ Seri AustinMount Austin, Tebrau & PonderosaBumi: SPA price 15% lower
 KSL RiverhausIskandar Puteri, Bukit Indah & Second LinkBumi: SPA price 15% lower
 KSL D’Secret Garden 2 @ KempasTampoi & KempasBumi: SPA price 15% lower
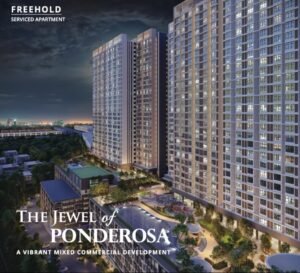
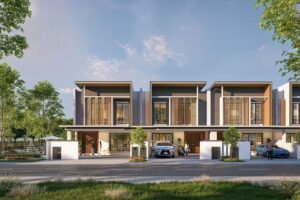 Meadow Heights @ Bandar TiramMount Austin, Tebrau & PonderosaBumi: SPA price 15% lower
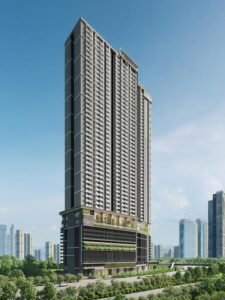 Aethera ResidencesJB City Centre & RTSBumi: SPA price 15% lower
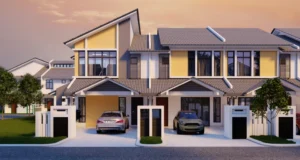 Bandar Tiram 3 Landed HomesMount Austin, Tebrau & PonderosaBumi: SPA price 15% lower
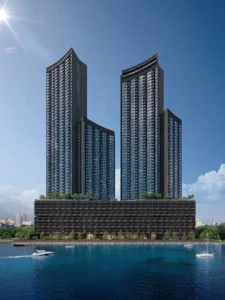 The Eclipse Johor BahruJB City Centre & RTSBumi: SPA price 15% lower
Full guide
Read the full guide
How is the monthly home loan instalment calculated?
Almost every home loan in Malaysia uses a reducing balance. Each month the bank charges interest (or profit, for Islamic financing) only on the amount you still owe. Your instalment stays the same, but the split changes: in the early years most of it goes to interest, and later most of it goes to the principal. That is why the first-12-months table shows so little principal at the start.
For a RM450,000 home with a 90% loan at 4% over 35 years, the loan is RM405,000 and the instalment is about RM1,793 a month. Over 35 years you pay about RM753,000, so roughly RM348,000 is interest or profit. A shorter tenure raises the monthly amount but cuts the total cost a lot.
Conventional loan or Islamic financing?
For the monthly figure, the maths is the same. The difference is the contract. A conventional loan charges interest on money lent. Islamic home financing uses a sale or partnership contract such as Musharakah Mutanaqisah or Tawarruq, and the bank earns profit instead of interest. Both usually float with the bank Standardised Base Rate (SBR), and Islamic contracts state a ceiling rate. Read more in our guide to Islamic home financing.
What is DSR and how do banks use it?
The debt service ratio (DSR) is the share of your net monthly income already going to debt. Banks add up the instalments in your CCRIS report, including car, personal and PTPTN loans, plus a share of your credit card limit, then add the new home instalment. If the total stays under their limit, commonly 60% to 70%, the loan can pass this test.
This calculator turns that test around. It takes your net income, subtracts your current commitments and shows the largest new instalment that fits. It then converts that instalment into a maximum loan and a maximum property price at your chosen margin.
DSR is only one part of the decision. Banks also check your CCRIS and CTOS record, job stability and the property value. If you were turned down before, see our first home guide for Johor Bahru.
How can you qualify for a bigger home loan?
- Settle a small personal loan or car loan before you apply. Every RM100 of commitment removed adds roughly RM22,500 to the loan you can get at 4% over 35 years.
- Lower unused credit card limits. A RM20,000 limit counts as RM1,000 a month even if you owe nothing.
- Apply with a spouse or parent as co-borrower. See joint home loans.
- Buyers without a fixed salary or with little savings may get up to 100% financing through the government-guaranteed SJKP scheme at participating banks (the original Skim Rumah Pertamaku closed to new applications in April 2023). See SJKP and Skim Rumah Pertamaku.
Related reading: new homes in Johor RM300k–RM500k, all projects.
Frequently asked questions
Is the 4% rate right for me?
It is a planning figure. Most home loans and Islamic financing in late 2026 are priced as the bank SBR plus a spread, and your offer letter shows the actual rate. Change the rate box to see the effect.
Should I choose 35 years?
A 35-year tenure gives the lowest instalment and the best DSR, but the highest total interest or profit. Many buyers take 35 years and make extra payments when they can, if the loan allows it without penalty.
Do banks use gross or net income for DSR?
Most banks use net income, after EPF, SOCSO and tax. Some banks allow a higher DSR limit for higher incomes. Tick the EPF box to follow the usual practice.
Why does my credit card count when I owe nothing?
Banks assume you could use the full limit, so many count about 5% of the limit as a monthly commitment. Cancelling or lowering cards you do not use can raise the loan you qualify for.
Does the Bumi discount change my loan?
Yes. The bank lends on the Bumi SPA price, so both the loan and the instalment are lower. Try our Bumi discount calculator.
Sources: CIMB: understanding DSR (seen 17 Nov 2026); Bank Negara Malaysia: 70% LTV for the third housing loan (3 Nov 2010); Bank Negara Malaysia: maximum tenure 35 years (5 Jul 2013)
Not sure which numbers apply to you? Send us your budget and the area you like. We reply with suitable new homes in Johor.
WhatsApp 018-989 6881